Most owners can tell you this morning's bank balance. Far fewer can tell you which week in the next three months is the tight one, or how tight it will be.
The bank balance answers the first question well. It is close to useless for the second, and the second is the one that decides whether payroll, a supplier payment or an equipment purchase is safe.
That is what a 13-week cash flow is for, and it is also why so many of them get built once and quietly abandoned.
Key Takeaways
- You check the bank balance to decide what you can pay this week, and it has surprised you more than once.
- You have a cash forecast, but it hasn't been updated since the person who built it got busy.
- A big payment you can't move, like a supplier bill, a tax payment or a truck, shows up as a surprise instead of a line you saw weeks ago.
- You have a line of credit or savings you never count, so you don't know how much room you actually have.
Take the Financial Control Score Quiz
7 questions. About a minute. See where your business actually stands.
What Is a 13-Week Cash Flow?
A 13-week cash flow is a week-by-week forecast of the cash coming into and going out of your business over the next quarter, updated every week with what actually happened. It replaces the bank balance as the number you make decisions from, because it shows the tight week before you are in it.
Thirteen weeks is long enough to see a quarter's worth of payroll runs, supplier terms, tax payments and seasonal swings, and short enough that each week can be forecast with real dates instead of averages. Each week starts with actual cash, adds expected receipts, subtracts expected payments and lands on an ending balance. When a week ends, its forecast is replaced with actual results and a new week is added at the far end.
It is not the same as your P&L. A month can be profitable and still leave you short, because profit and cash move on different clocks. The 13-week cash flow lives entirely on the cash clock.
Why Do Most 13-Week Cash Forecasts Stop Being Used?
Because nobody owns the weekly update, and the forecast drifts away from the bank until no one trusts it. A forecast built once and refreshed when someone remembers is worse than none: it gives a confident number that is weeks out of date.
The drift usually starts with inputs. Expected receipts come from an aging report that doesn't reflect what customers actually do. Bookkeeping runs a few weeks behind, so the starting point is already stale. Large irregular payments, like a quarterly tax bill, an insurance renewal or a piece of equipment, never make it onto the sheet because they don't come through the normal payables run.
Then a week goes by without an update, then two. By the time someone opens the file again, the bank and the forecast disagree, and fixing it feels harder than ignoring it.
What Does a 13-Week Cash Flow Catch That a Bank Balance Doesn't?
It catches the problems that live between the bank balance and the books: errors in what you think you have, payments you can't move, and room you didn't know you had. Three companies we work with show one of each.
Cash That Wasn't There
An automotive service company with several locations was building its first 13-week forecast while its outside bookkeepers ran about two weeks behind. The first pass turned up a duplicate account in the books that had been overstating cash by more than $100,000. The owner said he had very little trust in the accounting and no way to check it himself. The same forecast surfaced a past-due sales tax balance of nearly $90,000. Instead of paying it in one lump, the company set up a paydown over several months.
A Payment That Couldn't Move
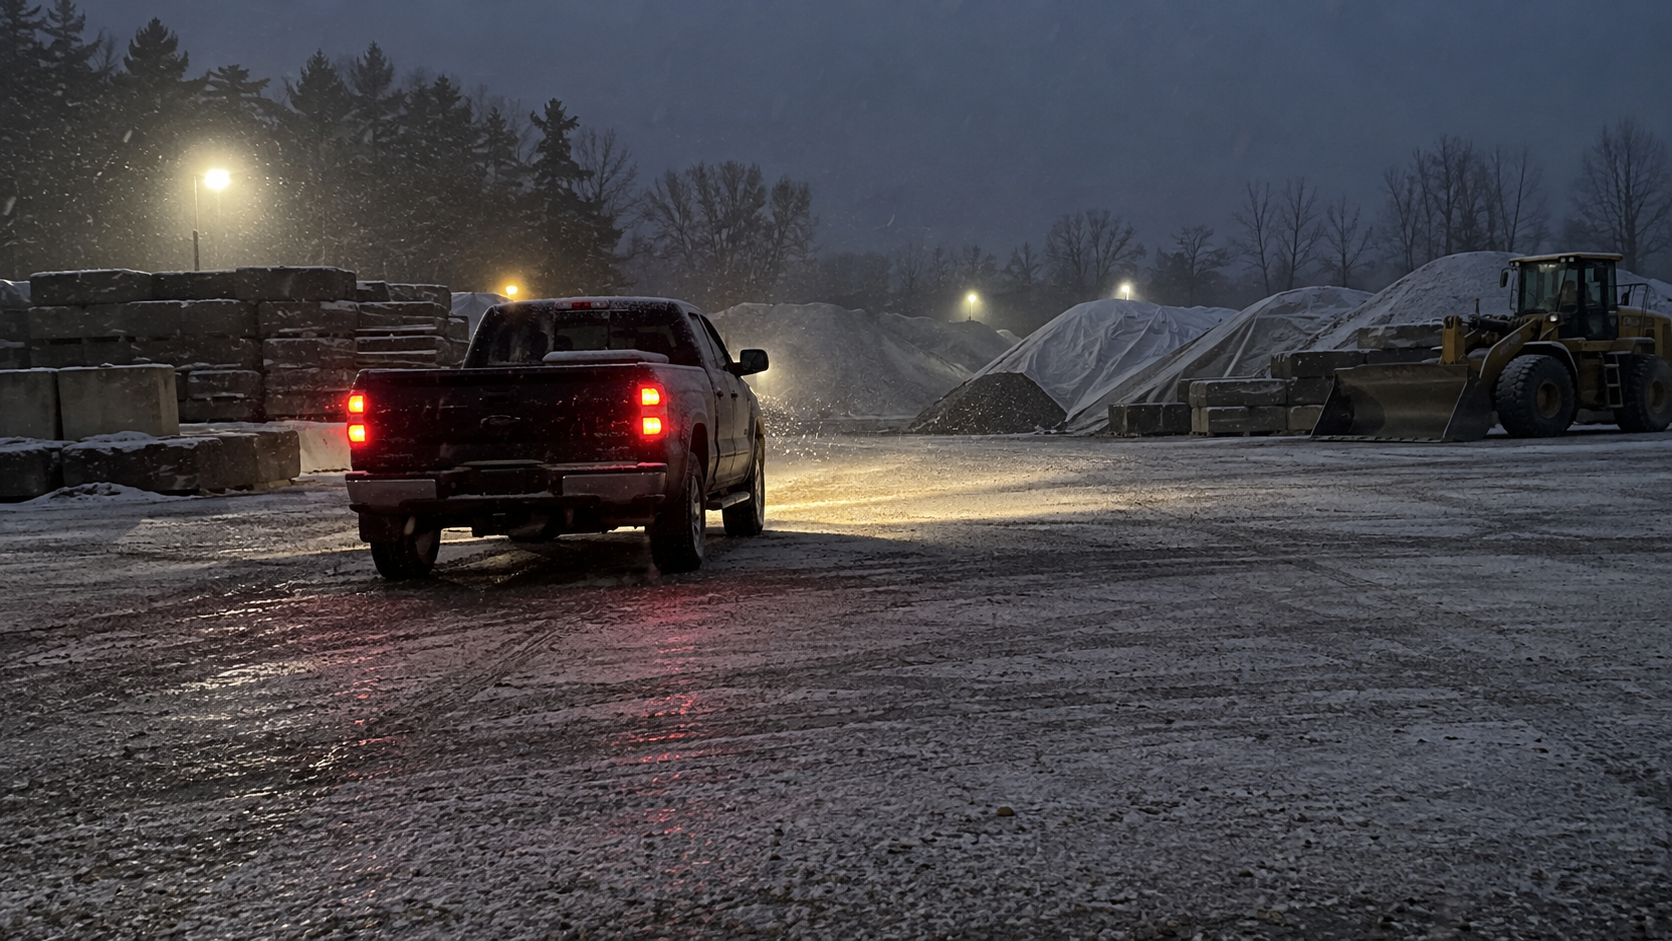
A landscape supply company we work with runs on a seasonal cycle: contract salt moves in the fall and early winter, and the risk is a January without snow. Its 13-week forecast was tight. A supplier payment well into six figures could not be late, another key vendor had capped its credit, and a planned truck purchase was competing for the same cash. Because all three sat in the same forecast, the decision was clean. The truck purchase was deferred, an older truck went up for sale, and the company decided that hauling salt with its own trucks wasn't worth it.
A Reserve Nobody Was Counting
A specialty coatings contractor we work with built a new 13-week forecast this fall. The first week showed about $40,000 coming in against payroll, payables and other outflows that left the week roughly $48,000 short. About $250,000 in savings sat outside the forecast entirely. Leaving a reserve out can be a reasonable choice, as long as everyone reading the forecast knows the reserve exists and what would trigger using it. The weekly update is moving to a named person on their staff once the first versions settle.
We hear the same pattern elsewhere: a commercial general contractor's controller who said she could barely produce a weekly cash flow, a restoration owner who moved money out of savings while a line of credit sat unused, and a design-build firm whose controller was still learning how payables flowed into the forecast.
What Should a 13-Week Cash Flow Include?
Every cash movement with a date attached: customer receipts in the week you actually expect them, payroll on its real run dates, supplier and subcontractor payments by due date, and debt payments, taxes, owner draws and planned equipment purchases in the week they will clear. Below the ending balance, list unused credit and any reserves separately, so you can see both operating cash and total room.
Three details make it usable. Start every week from the actual bank balance, not last week's forecast. Forecast receipts from each customer's real payment history rather than the terms on the invoice. And keep a variance column showing what you forecast for last week next to what happened, because that column is where trust comes from.
Then set a minimum cash line, the balance you never want to drop below, and highlight any week that crosses it. That turns the forecast from a report into an early warning.
Who Should Own the 13-Week Cash Flow?
One named person in finance, usually the controller, should update it every week on the same day, and the owner should review it in a standing weekly meeting. The CFO's job is to build it, set the assumptions and teach the team to keep it honest, not to be the only person who can run it.
The owner's job in that meeting is to make decisions, not to audit the spreadsheet. Which payment moves. Which invoice gets a phone call. Whether the equipment purchase waits a month.
What Changes When You Trust the Next 13 Weeks?
Decisions move earlier. The tight week shows up five or six weeks out, when you can still ask a customer for a deposit, stagger a purchase or line up the credit line, instead of the Thursday before payroll.
Conversations with lenders get easier, because you can show them the forecast and how closely last quarter's version matched reality. And the owner stops checking the bank balance three times a day, because the number that matters is already on the page.
How Long Does It Take to Build a 13-Week Cash Flow You Can Trust?
In our experience the first version is the easy part, and trust takes longer. It comes from comparing forecast to actual every week until the variances are small and explainable, which usually takes a couple of months of steady updates.
That is why we build the forecast with your team rather than for it. We set it up, run it alongside your controller through the first stretch, and hand over the weekly update once the numbers hold. The goal is a forecast your people can run without us, and an owner who knows the tight week before it arrives.
Your Next Step
If you can't name your tightest week, you don't have a cash forecast yet.
The Financial Control Score Quiz is 7 questions and takes about a minute, and cash visibility is one of the areas it scores. If you would rather have someone build the first version with your team, book a 30-minute call.
Common Questions
Frequently Asked Questions
What Is a 13-Week Cash Flow Forecast?
It is a week-by-week projection of cash receipts and payments over the next 13 weeks, updated weekly with actual results. Each week starts with actual cash, adds expected receipts, subtracts expected payments and shows an ending balance, so a shortfall shows up weeks before it happens.
How Do You Build a 13-Week Cash Flow?
Start with today's actual bank balance. List expected customer receipts by week based on real payment history, then payroll on its run dates, supplier payments by due date, debt service, taxes, draws and planned purchases. Calculate each week's ending balance, then compare forecast to actual every week and adjust.
Why Use 13 Weeks Instead of a Monthly Forecast?
A monthly forecast hides the timing inside the month, and most cash problems are timing problems. A week with two payrolls and a large supplier payment can come up short even in a month that looks fine overall. Thirteen weekly columns cover a full quarter at the level where those collisions show up.
How Often Should a 13-Week Cash Flow Be Updated?
Every week, on the same day, by the same person. Replace last week's forecast with actual results, add a new week at the end and explain any large variance. A forecast updated only when someone remembers loses trust quickly and usually stops being used within a few months.
Should a Line of Credit Be Included in a Cash Flow Forecast?
List it, but separately. Show operating cash on its own, then show unused credit and reserves below it, so you can see both what the business generates and how much room you have. Mixing them hides whether the business is funding itself or quietly leaning on borrowed money.