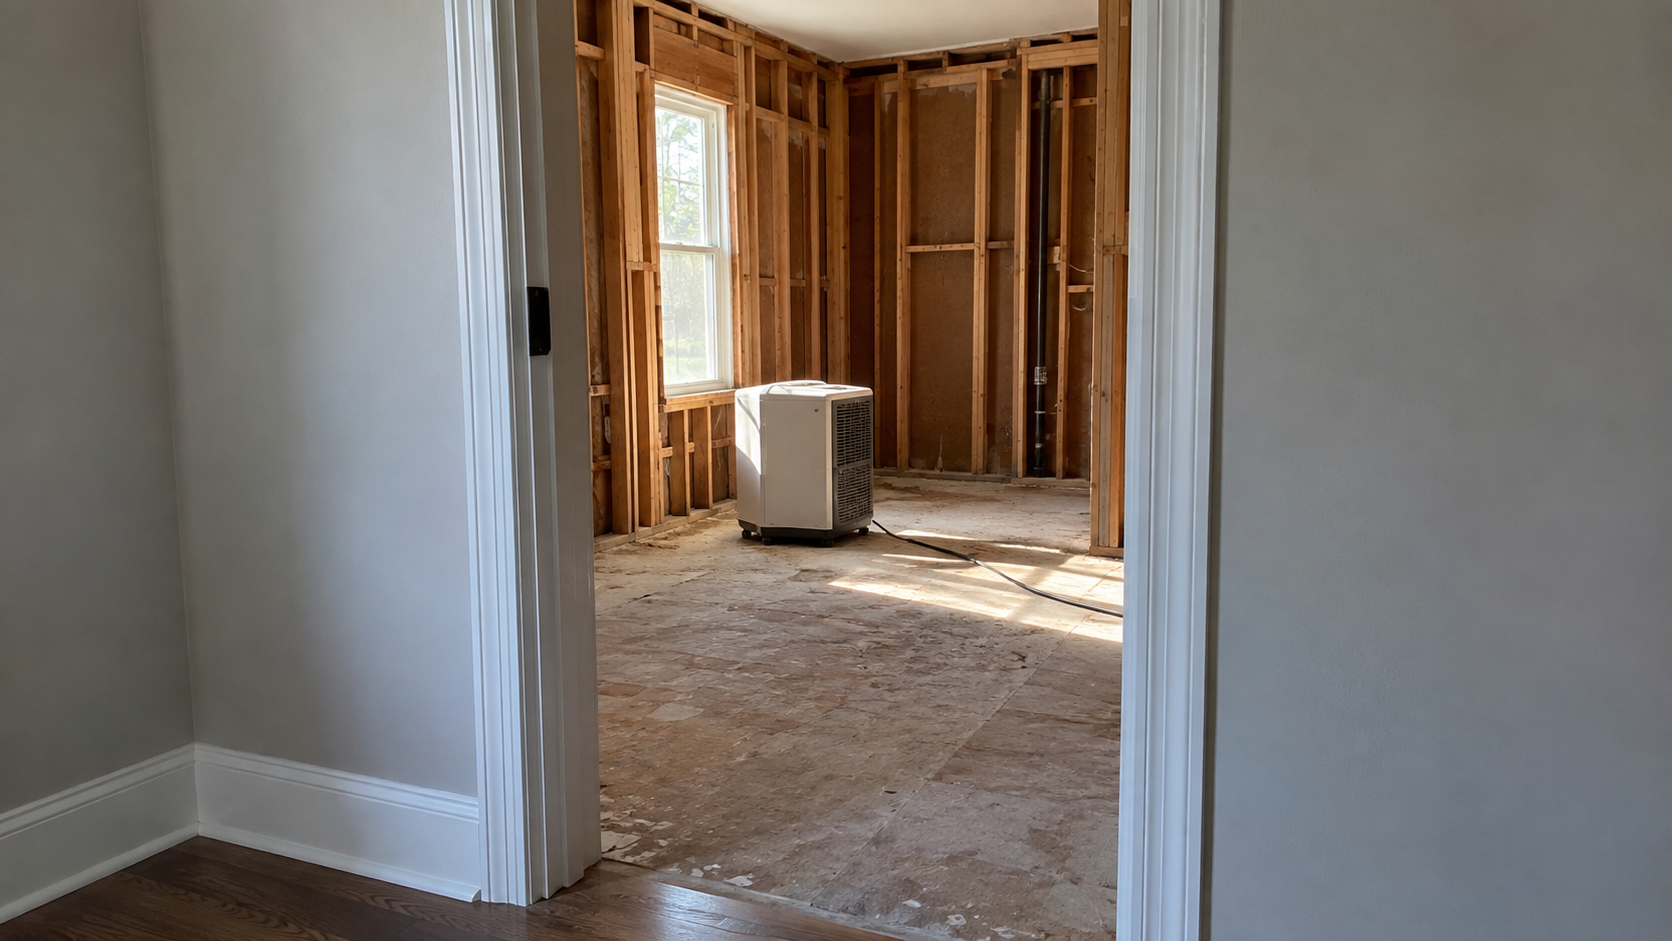
A rebuild job can show a 45% gross margin in your job management software and still lose money for the company.
Nobody keyed anything in wrong. The job report and the P&L are measuring two different things, and in most restoration companies nobody has reconciled them.
That gap is why restoration job profitability is one of the hardest numbers in the industry to trust, and one of the most expensive to get wrong.
Key Takeaways
- Your job reports show healthy margins on reconstruction, but the company's bottom line looks nothing like the average of your jobs.
- You can quote your blended gross margin, but not your mitigation margin and your rebuild margin as two separate numbers.
- Commissions or bonuses get paid on job margin before every vendor and subcontractor bill has arrived.
- The labor rate in your job software was set once, years ago, and nobody has checked it against payroll since.
Take the Financial Control Score Quiz
7 questions. About a minute. See where your business actually stands.
Why Doesn't Restoration Job Profitability Match the P&L?
Because the job report usually leaves out costs the P&L includes: the full burden on field labor, the coordinators and project managers who touch every claim, and vendor and subcontractor bills that arrive weeks after a job is marked complete. Each one is small on a single job. Across a year of rebuild work, together they can take a 40% job margin down to single digits.
Job management software is built to estimate and track jobs, and it does that well. But it only knows what you tell it. If the labor rate entered when the system was set up was too low, every job carries that error forward. If coordinators are paid out of overhead, no job ever sees their cost. If a subcontractor's final bill shows up six weeks after closeout, the job's margin was already reported, celebrated and paid on.
The P&L eventually catches all of it, because the P&L sees every dollar. It just can't tell you which jobs or which line of work caused the gap.
Why Do Mitigation and Reconstruction Need Separate Margins?
Because they are different businesses with different cost structures. Mitigation runs on your own crews and equipment and usually carries a much higher gross margin; reconstruction runs largely on subcontractors, carries a lower margin and takes on more timing risk. Blended into one number, a strong mitigation month can hide a losing rebuild month.
The mix also moves. A company that was mostly reconstruction last year can be mostly mitigation this year after a busy storm season or a change in program work. If gross margin is reported as one company-wide number, the mix shift looks like a change in performance, and leadership spends a quarter chasing the wrong problem.
Separate margins change pricing conversations too. When you know rebuild margin on its own, you can decide which jobs, programs and referral partners are worth taking on the terms offered, and which only look acceptable because mitigation is carrying them.
What Does the Gap Look Like Inside a Real Restoration Company?
It looks like healthy job reports and a disappointing year-end, and it shows up at every size. Three restoration companies we have spoken with or work with show how.
Rebuild Margins in the 40s, Department Margins in Single Digits
We spoke with a multi-location restoration company that had grown from about $3 million to roughly $9 million in a few years, with reconstruction making up close to two-thirds of revenue. Its job management software showed rebuild jobs at 40% to 50% gross margin. Fully loaded at the department level, rebuild margin was in single digits. Part of the gap traced back to setup: when the software was first configured, the labor burden had been entered at a rate the owner later called unrealistically low, so every job looked better than it was. Net margin had gone from about 10% a year earlier to a loss. The owner's goal was simple and familiar: to know the true margin once everything was counted.
Strong at the Job Level, Invisible on the P&L
We spoke with a two-office restoration company where mitigation jobs ran above 60% gross margin and rebuild jobs around 41% at the job level. Company gross margin sat near 31%, and net profit was 1% to 2% against a goal of 9%. Their operations leader summed it up in a sentence: they could see margin at the job level, but not on the P&L. The accounting was split by location rather than by line of work, the rebuild margin on the job report was calculated before cost of sales, and the gross margin on their scorecard left out the coordinators who manage every claim.
A Forecast Built on Two Margins Instead of One
A restoration client of ours operating in several markets rebuilt its forecast around a separate margin for each line of work, roughly 38% on repairs and 70% on mitigation, instead of one blended rate. In the same review it changed how production staff are paid. Commissions now require both a minimum weekly revenue level and a minimum gross margin, with different margin thresholds for different roles, so nobody is paid on volume that did not earn its margin.
That last point matters more than it looks. In several restoration companies we have worked with, commissions were calculated from the job report before every vendor bill had arrived, which means the company paid out on margin that later disappeared.
What Is Missing From Most Restoration Profitability Reports?
A fully loaded margin for each line of work, reported monthly on the P&L, using the same cost definitions as the job reports. Most companies have one half of that: job reports with incomplete costs, or a P&L that cannot separate mitigation from reconstruction.
Closing the gap takes four pieces. First, set up the accounting so revenue and direct cost post separately for mitigation, reconstruction and contents. Second, check the labor burden rate in your job software against actual payroll costs at least once a year. Third, decide where coordinators and project managers belong, either charged to jobs or allocated by line of work, and apply that rule every month. Fourth, accrue expected vendor and subcontractor bills when a job is marked complete, so the margin reported at closeout is the margin you actually earned.
Then reconcile. Each month, gross margin by line of work on the P&L should be explainable from the job reports. When it isn't, the difference is the most useful number in the building.
What Changes When You Can See Margin by Line of Work?
Pricing gets sharper. You can see which programs, carriers and referral partners produce rebuild work worth having, and which only look acceptable because mitigation is carrying them.
Pay plans start rewarding the right thing. Commissions and bonuses tied to fully costed margin stop paying out on jobs that later turn out to have lost money.
And growth decisions get easier. Whether to add a location, a rebuild crew or a new service becomes a question you can answer with each line's own margin, not a blended average that hides the weak one.
How Should a Restoration Company Report Profitability?
Our view is two margins, one reconciliation and a monthly rhythm. Mitigation and reconstruction each get their own fully loaded gross margin on the P&L. The job reports get reconciled to those numbers every month. And pay plans are tied to the reconciled margin, not the job report's first draft.
That is the core of how we approach fractional CFO work for restoration companies. The software rarely needs replacing. What it needs is a labor rate that matches payroll, a rule for where overhead roles land, and someone who checks every month that the job reports and the books still agree.
Your Next Step
If you can't state mitigation and rebuild margin as two separate numbers, start there.
The Financial Control Score Quiz is 7 questions and takes about a minute, and profit confidence is one of the areas it scores. If you would rather walk through your own job reports with us, book a 30-minute call.
Common Questions
Frequently Asked Questions
What Is a Good Gross Margin for a Restoration Company?
It depends on the mix of work. Mitigation done with your own crews usually carries a much higher gross margin than subcontracted reconstruction, so a single company-wide target hides more than it shows. Set a separate target for each line of work and judge the blended number against your actual mix.
Why Is My Job Software Margin Higher Than QuickBooks?
Usually because the job software is missing costs the books include, such as full labor burden, coordinator and project manager time, or vendor bills that arrived after the job closed. Check the labor rate in the software against payroll, then reconcile the two margins by line of work every month.
Should Restoration Companies Track Mitigation and Reconstruction Separately?
Yes. The two lines have different cost structures, margins and timing risk, and a blended margin hides which one is driving results. Post revenue and direct costs for each line separately in the accounting system so the P&L shows a fully loaded margin for mitigation and for reconstruction every month.
What Costs Should Be Included in Restoration Job Costing?
All direct labor at its full burdened rate, materials, equipment, subcontractors and any vendor bills expected after completion. Decide as a rule whether coordinators and project managers are charged to jobs or allocated by line of work. Whatever the rule, apply it the same way every month so margins stay comparable.
Should Commissions Be Based on Gross Profit in Restoration?
Gross profit is a better basis than revenue, but only if it is fully costed. Paying on a job report before vendor bills and full labor burden have landed means paying on margin that may disappear. Add a margin threshold and pay after the job's costs are complete.