Cost Reporting in Construction: Why Nobody Trusts the Report
Reading Time:
23 minutes
Ask a contractor what their cost reports say and you will often get a pause, then a qualification. The report exists. It goes out. Nobody entirely believes it, and everybody has quietly built a workaround for that, which is the part that actually costs money.
Key Takeaways
- Construction cost reports are late for one dominant reason, and it is not accounting. It is that approvals have not happened yet.
- When invoices are not approved on time, accounting stops reporting and starts projecting, and a projected payable is an estimate wearing the clothes of a fact.
- The real cost of a late cost report is not the delay. It is that you commit the next month before you learn about the last one.
- A trustworthy cost report is not a perfect one. It is one where somebody can explain every gap in a sentence.
What Is Cost Reporting in Construction?
Cost reporting in construction is the process of comparing what a job was budgeted to cost against what it has actually cost so far, plus what it will still cost, while the job is running.
That last clause is the whole point and the part most often lost. A report that tells you what a finished job cost is history. A cost report is supposed to be a forecast you can still act on, which means it has to carry committed costs and a current estimate of cost to complete, not just invoices received.
It is distinct from work-in-progress reporting, though the two are related. WIP is an accounting output that determines how much revenue you recognize this period. Cost reporting is an operating output that determines whether you keep bidding work like the last one. Contractors who conflate the two usually end up with a WIP schedule the accountants believe and project managers ignore.
Why Are Construction Cost Reports Always Late?
Because the report is waiting on approvals that have not happened, and the approvals sit with people whose primary job is not reporting.
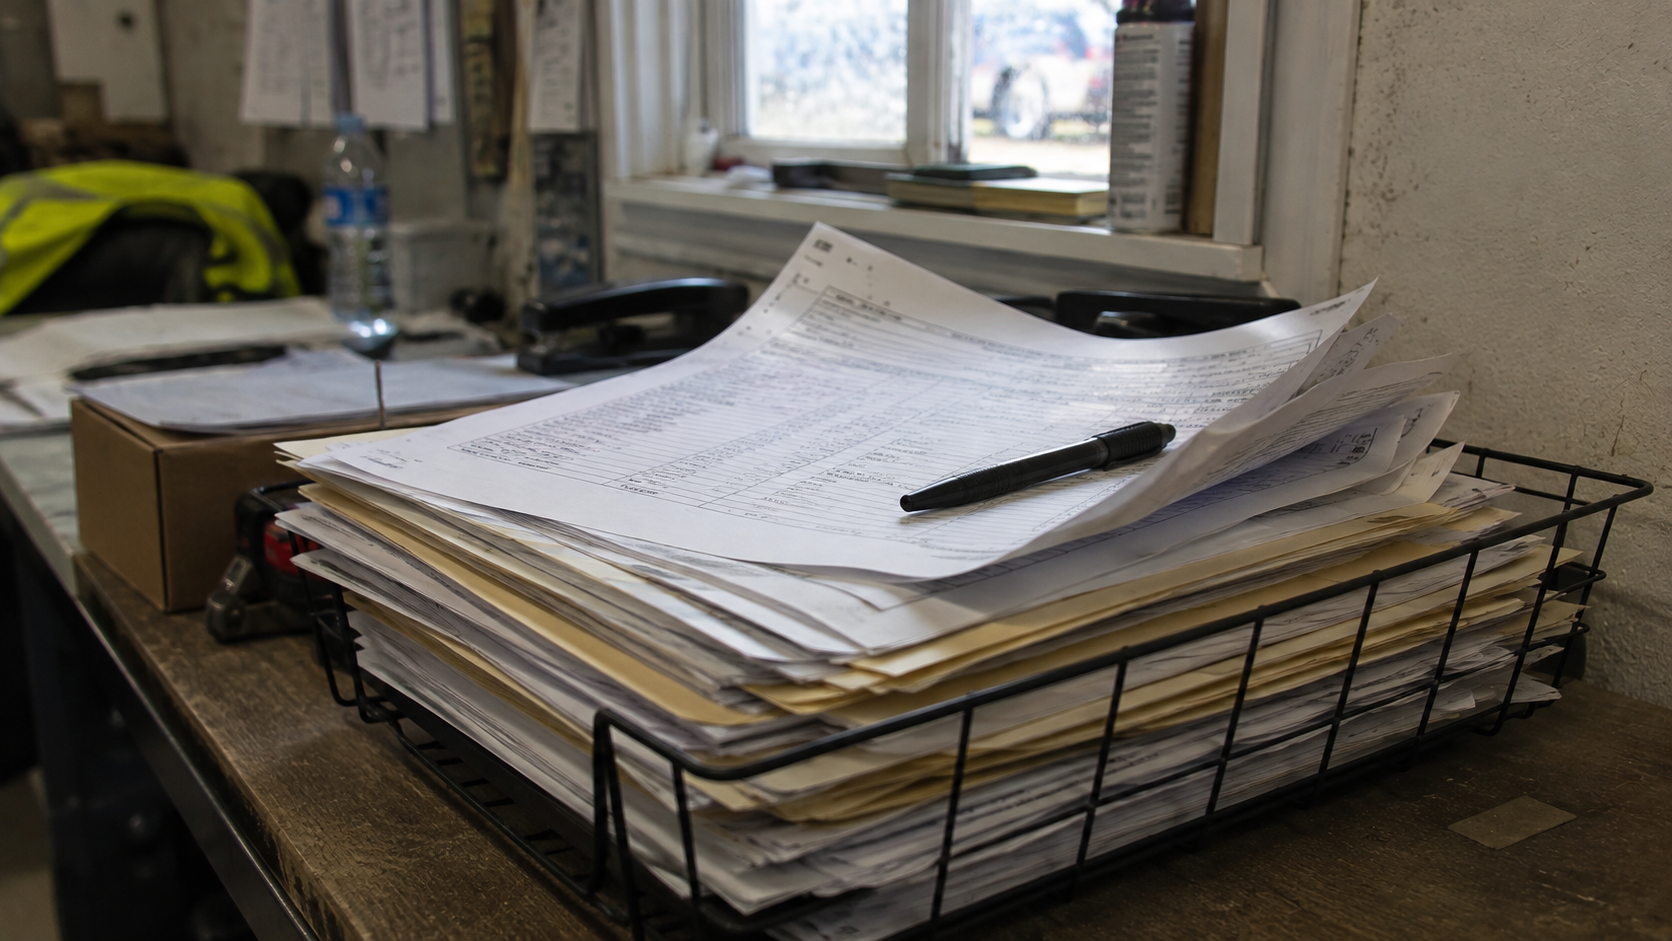
The sequence is consistent. A subcontractor or vendor invoice arrives. It needs a project manager to confirm the work was performed and the amount is right. The project manager is on a site, and approving invoices is the least urgent thing on their list on any given day. Accounting cannot close what it cannot post, so it waits. Then, at some point, it stops waiting.
A commercial contractor we looked at had exactly this pattern and named the consequence precisely: because project managers were not approving subcontractor and vendor invoices in the month they arrived, accounting worked backward and projected payables instead of reporting them. Their work-in-progress was running roughly a month behind as a result. And a prior month could stay open long enough that a loss from two months earlier surfaced only after the following month had already been bid and staffed.
That is the mechanism, stated plainly. It is not an accounting capability problem. Every business in that story was competent. The report was late because a control that lives in operations had not been enforced, and reporting is downstream of operations in a way that most contractors do not fully price.
It is worth being precise about who this indicts, because the reflex is to blame accounting and that is almost always wrong. Accounting is the last stop in a chain that starts on a job site. If the invoice was not approved, the cost cannot post. If the cost did not post, the report cannot be right. Every attempt to fix report timing inside the accounting function alone runs into that ceiling within a month.
Why Are WIP Reports Inaccurate in Construction Job Costing?
Because costs arrive after the period they belong to, and every mechanism designed to correct for that involves somebody's estimate.
Three specific causes account for most of it. Committed costs are not captured when a subcontract is issued, so the job looks cheaper than it is until the invoice lands. Cost to complete is a project manager's judgment, and an optimistic project manager produces an optimistic WIP without anyone lying. And labor is costed at a rate that does not include burden, so every hour is quietly understated.
There is a fourth cause that is less discussed and more damaging: corrections landing in the wrong period. A specialty contractor we work with had adjustments dating back two and three years finally post, all at once, into a single month's income statement. That month's result was mostly historical cleanup. The periods those costs actually belonged to stayed wrong, and anyone reading that month in isolation would have drawn a conclusion about current operations that was not supported by anything current.
What Happens When Nobody Trusts the Cost Report
People stop using it and start running the business off something else, usually a spreadsheet somebody maintains privately, and the two versions drift.
A facilities and construction company we spoke with showed how expensive this gets when a control is missing. A revision to their job-cost labor rates never reached the person entering them. The books carried the wrong rates for two months before anyone caught it. Correcting it meant a line-by-line audit of roughly twelve hundred labor entries, which took about five weeks of the owner's own attention. Two months of bad rates cost five weeks of the most expensive person in the building.
What the owner asked for afterward was not a better report. It was reporting he did not personally have to verify - which is a different request, and a more honest description of what most contractors actually want.
The compounding cost is decision latency. If your cost report tells you a job class is underperforming three months after it started, you have already bid the next three the same way. That is the real bill for a late report, and it does not appear on any line of the income statement.
How to Improve Job Costing Accuracy in Construction
Fix the approval clock before you touch anything else, because every other improvement is downstream of it.
Set a hard rule that vendor and subcontractor invoices are approved in the month they arrive, name who is accountable when they are not, and report the approval backlog weekly as its own number. Most contractors track cost accuracy and never track the thing that determines it.
Then capture committed costs at commitment rather than at invoice, so an issued subcontract hits the job the day it is signed. Move labor to a loaded rate sourced from payroll rather than a figure typed in during a prior year. And require cost to complete to be updated on a schedule, by name, so an unrevised estimate is visible as an unrevised estimate rather than passing as current.
None of that requires new software, which is worth saying because the reflex in construction finance work is to reach for a system when the constraint is a habit.
There is one more control worth adding, and it costs nothing. Publish the close date and the approval deadline on the same calendar everyone else uses, and treat a missed approval the way you would treat a missed submittal. Most contractors have rigorous processes for operational deadlines and no equivalent for financial ones, and the reporting reflects exactly that difference in seriousness.
What a Trustworthy Construction Cost Report Looks Like
It arrives on a date you can plan around, it carries committed costs and cost to complete, and somebody can explain every gap in it in one sentence.
That last criterion is the useful one, because perfect accuracy is not available. Costs will always arrive late and estimates will always be estimates. What separates a report you can run a business on from one you cannot is whether the person presenting it can tell you what is missing and why, without being asked.
The practical test is to ask for three things at your next review: what is not yet in this report, which numbers in it are estimates rather than actuals, and what would have to change for it to land a week earlier. If nobody can answer all three, the report is not the problem. The absence of an owner is.
It also has to be read by the people who can change the outcome. A cost report that goes to accounting and the owner but not to the project managers whose approvals and cost-to-complete estimates drive it is a scorecard nobody being scored can see. Putting the same report in front of the people generating the numbers usually improves the numbers before anyone changes a process.
Your Next Step
A Late Cost Report Means You Bid Next Month Before You Learned About Last Month
If your last cost report arrived after you had already committed crews and bids for the following period, that is a timing problem with a specific cause, and the timeliness of your financial information is one of the dimensions the Financial Control Score Quiz scores directly.
Common Questions
Frequently Asked Questions
Why Are WIP Reports Inaccurate in Construction Job Costing?
Mainly because committed costs are not captured when a subcontract is issued, cost to complete relies on a project manager's judgment, and labor is often costed without burden. Corrections landing in the wrong accounting period compound all three and make a single month unreadable.
How Do You Improve Job Costing Accuracy in Construction?
Start with the approval clock. Require vendor and subcontractor invoices to be approved in the month they arrive and report the approval backlog weekly. Then capture committed costs at commitment, use a loaded labor rate from payroll, and update cost to complete on a named schedule.
How Do You Prevent Miscoded Expenses in Construction Job Cost Reports?
Restrict who can create cost codes, make the job and cost code mandatory at entry rather than corrected afterward, and reconcile job cost to the general ledger monthly. Persistent miscoding usually means the code structure does not match how the work is actually sold.
How Do Construction Companies Track Job Costs in Real Time?
By capturing field labor daily and entering committed costs at the moment a subcontract or purchase order is issued. Genuine real-time financial job cost is not achievable because vendor invoices and payroll burden arrive later, so current-within-a-week is the realistic target.
How Do Construction CFOs Manage Job Cost Tracking?
By owning the calendar rather than the spreadsheet. A construction CFO's job is to make the close date predictable, keep the approval backlog visible, ensure the WIP ties to the financial statements, and say plainly which numbers in the report are not yet reliable.