How Much of Your Backlog Is Actually Money?
Reading Time:
22 minutes
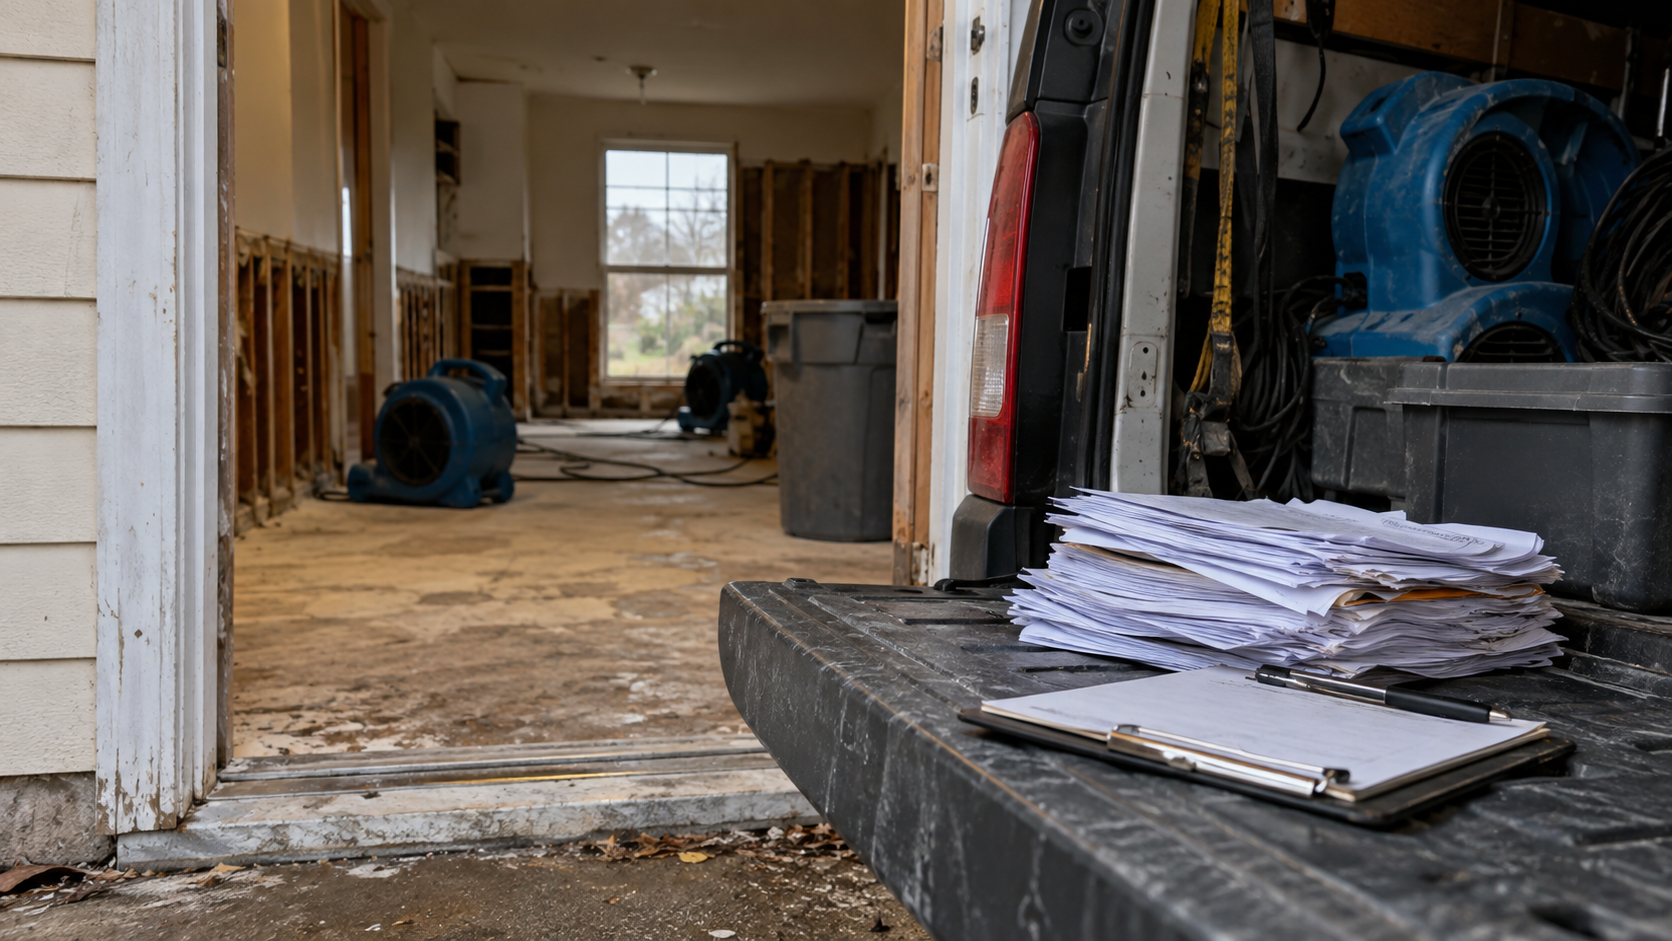
A restoration contractor forecast just over a million dollars of jobs closing inside three weeks. Roughly half of it could actually be billed in that window.
Nothing had gone wrong on those jobs. Crews were where they were supposed to be, the work was moving, and the forecast had been built from the company's own system. The gap sat between finishing work and being allowed to invoice for it, and no report in the business measured that gap.
Key Takeaways
- You can state your backlog total but not the week each piece turns into cash
- Your aged receivables include balances that were never collectible in the first place
- Jobs finish, then wait on a signature, an inspection, or a customer selection before anyone can invoice
- Nobody owns the step between work complete and invoice sent
What Does a CFO Advisory Service Do for a Restoration Contractor?
It connects production to cash, which in restoration means making the steps between finishing work and collecting on it measurable and owned by someone. Everything else follows from that.
The practical test is whether WIP, billing readiness, and receivables get reviewed together on a fixed cadence, or separately at month end by different people. Reviewed separately, each one looks defensible. Reviewed together, the gaps become obvious and someone has to close them.
This is also why the work does not look like reporting. A firm that hands over a better monthly package has improved the description of the problem without touching the problem.
Why Does Restoration Backlog Take So Long to Turn Into Cash?
Because billing is gated by operational steps that finance does not control and usually does not measure. A job can be finished and still unbillable for weeks while it waits on an inspection, a signed change order, a carrier approval, or a customer picking a finish.
One restoration client of ours reviewed a backlog forecast showing roughly $1.078 million of jobs closing across a three-week window. About half of it was genuinely billable in that period. Separately, roughly $164,000 of pre-production work carried dates inside the month with about $130,000 of it still unconverted, and several completion dates had been set to the last day of the month because that was the target, not because that was when the work would finish.
That is the pattern worth internalizing. Backlog does not become cash on completion. It becomes cash on billing, and billing waits on steps most finance teams never put a number against.
What Should You Ask a CFO Advisory Firm About Receivables?
Ask how they establish which receivables were ever collectible, before they ask anyone to chase them. An aged AR report mixes real debts with amounts that are still being earned and with artifacts of how the system was set up, and chasing the second and third categories burns credibility with customers who do not owe anything.
At the same restoration client, a weekly cash review found a customer payment that had been applied to the customer record rather than the invoice, which created a negative and left a July invoice showing unpaid for two months against a payment already received. A duplicate payment in the same period had never cleared the bank reconciliation. Neither was a collections problem. Both had been sitting inside a number the business was using to decide what it could spend.
The other half of the receivables question is whether anything could have been billed at all. At the same client, more than five accounts sitting in collections had no signed estimate or change order behind them, which meant those balances were not merely late - they were unenforceable until somebody went back for a signature. The response was to set a standard rather than chase harder: three contact attempts inside fourteen calendar days, then a written notice, with lien preparation starting immediately instead of waiting out the notice period.
The same review surfaced a carrier whose processing time had moved from ten to fifteen days out to thirty. Nothing in the business changed; the cash arrived later anyway. A firm that treats collections as an effort problem will miss that entirely.
What Should You Ask About WIP Visibility?
Ask whether the WIP schedule is used during the month or read after it. A schedule reviewed at close can explain what already happened; it cannot change anything, and the difference is not a matter of degree.
A commercial restoration contractor we began working with this year runs more than two hundred jobs a year and already had a capable accounting system holding the data. What leadership actually asked for at kickoff was better visibility into WIP, more accurate monthly scrubbing, and a clearer answer to who was accountable for productivity across job sites. The information existed. The rhythm that would have made it useful did not.
That is the more common situation by some distance. Very few companies at this size are missing data. Most are missing a standing meeting where someone has to act on it.
What Should You Ask About Cash Flow Control?
Ask what they do when work mix moves, because mix moves cash faster than volume does. Mitigation and reconstruction carry different margins and different collection speeds, so the same total revenue can produce very different cash depending on which one produced it.
One restoration client of ours saw mitigation revenue rise about $260,000 year over year with gross profit up roughly $550,000, while reconstruction revenue fell about $600,000 and its gross profit fell about $500,000. Total revenue moved roughly $350,000 — a number that badly understates what had happened underneath it. In the same review, a receipt of more than $100,000 aged past ninety days landed in September rather than August, moving a month's result without any operating change at all.
Any firm can read a revenue line. The question is whether they can tell you what your mix is doing to your collection speed, and what that implies for the next quarter rather than the last one. Our page on restoration-specific CFO work covers how that runs as an ongoing engagement.
What Does Backbone CFO Check Before Recommending a Move?
Whether the numbers can be trusted before anything gets built on them. A cash forecast sitting on a WIP schedule that has never been reconciled, or on an AR balance carrying amounts that were never owed, produces a confident wrong answer, and confident wrong answers are more dangerous than no answer because people act on them.
So the sequence is fixed. Test whether cost is landing on the right jobs. Reconcile WIP to the income statement. Establish which receivables are genuinely collectible and which are setup artifacts. Then build the forward view. Skipping to the forecast is the most common request and the one we most often decline in the first month.
It is worth saying plainly that this order is slower than what most firms will promise you in a proposal.
Who Is This Not the Right Fit For?
A restoration company much under $10 million in revenue usually does not need embedded financial leadership and should not pay for it. At that size an owner can still hold the whole picture, and the annual cost is a genuine burden rather than an investment — we have walked prospects back from a signed proposal for exactly this reason.
It is also the wrong fit when the real problem is bookkeeping accuracy rather than decision-making. If the close is unreliable, a CFO layered on top will produce better-argued wrong conclusions. Fix the close first, with whoever is cheapest and fastest at fixing closes.
And it is the wrong fit for a company that wants a report rather than an argument. The work involves being told that a structure you built is now too expensive for the revenue it supports, which is not a comfortable conversation and is frequently the most valuable one.
Your Next Step
Backlog Is Not the Same Thing as Cash, and the Gap Has a Number
If you can state your backlog total but not the week each piece converts, that is the conversation to have. A discovery call is thirty minutes and ends with a straight answer about whether this is the right time for you. If you would rather start with a number, the Financial Control Score Quiz scores cash visibility in about a minute.
Common Questions
Frequently Asked Questions
What Should You Look For When Hiring a CFO Advisory Firm?
Ask how they will establish that your numbers are reliable before they build anything on them, and ask for the sequence they follow in the first ninety days. A firm that leads with a forecast rather than a reconciliation is selling the output and skipping the work that makes it true.
What Does a Fractional CFO Do for a Growing Restoration Company?
They connect WIP, billing readiness, receivables, and work mix into a decision rhythm leadership can actually run. The distinction from accounting support is that the job is forward-looking: deciding what to change about cash, margin, and capacity while the decisions are still open.
Is a Fractional CFO Worth It for a Restoration Contractor?
It depends far more on size and problem type than on enthusiasm. Above roughly $10 million in revenue, with work spread across mitigation and reconstruction, the answer is usually yes. Below that, or when the underlying issue is an unreliable close, it usually is not.
How Do You Know Whether Your Backlog Is Really Billable?
Test a single month. List every job forecast to complete, then mark what each one is waiting on before an invoice can go out. Anything waiting on an inspection, a signature, or a selection is not billable on the completion date, however the schedule reads.
How Often Should Restoration Receivables Be Reviewed?
Weekly, at a minimum, and line by line rather than in aging buckets. Aging totals hide the two categories that matter most: amounts that were never collectible, and amounts already paid but applied to the wrong record.